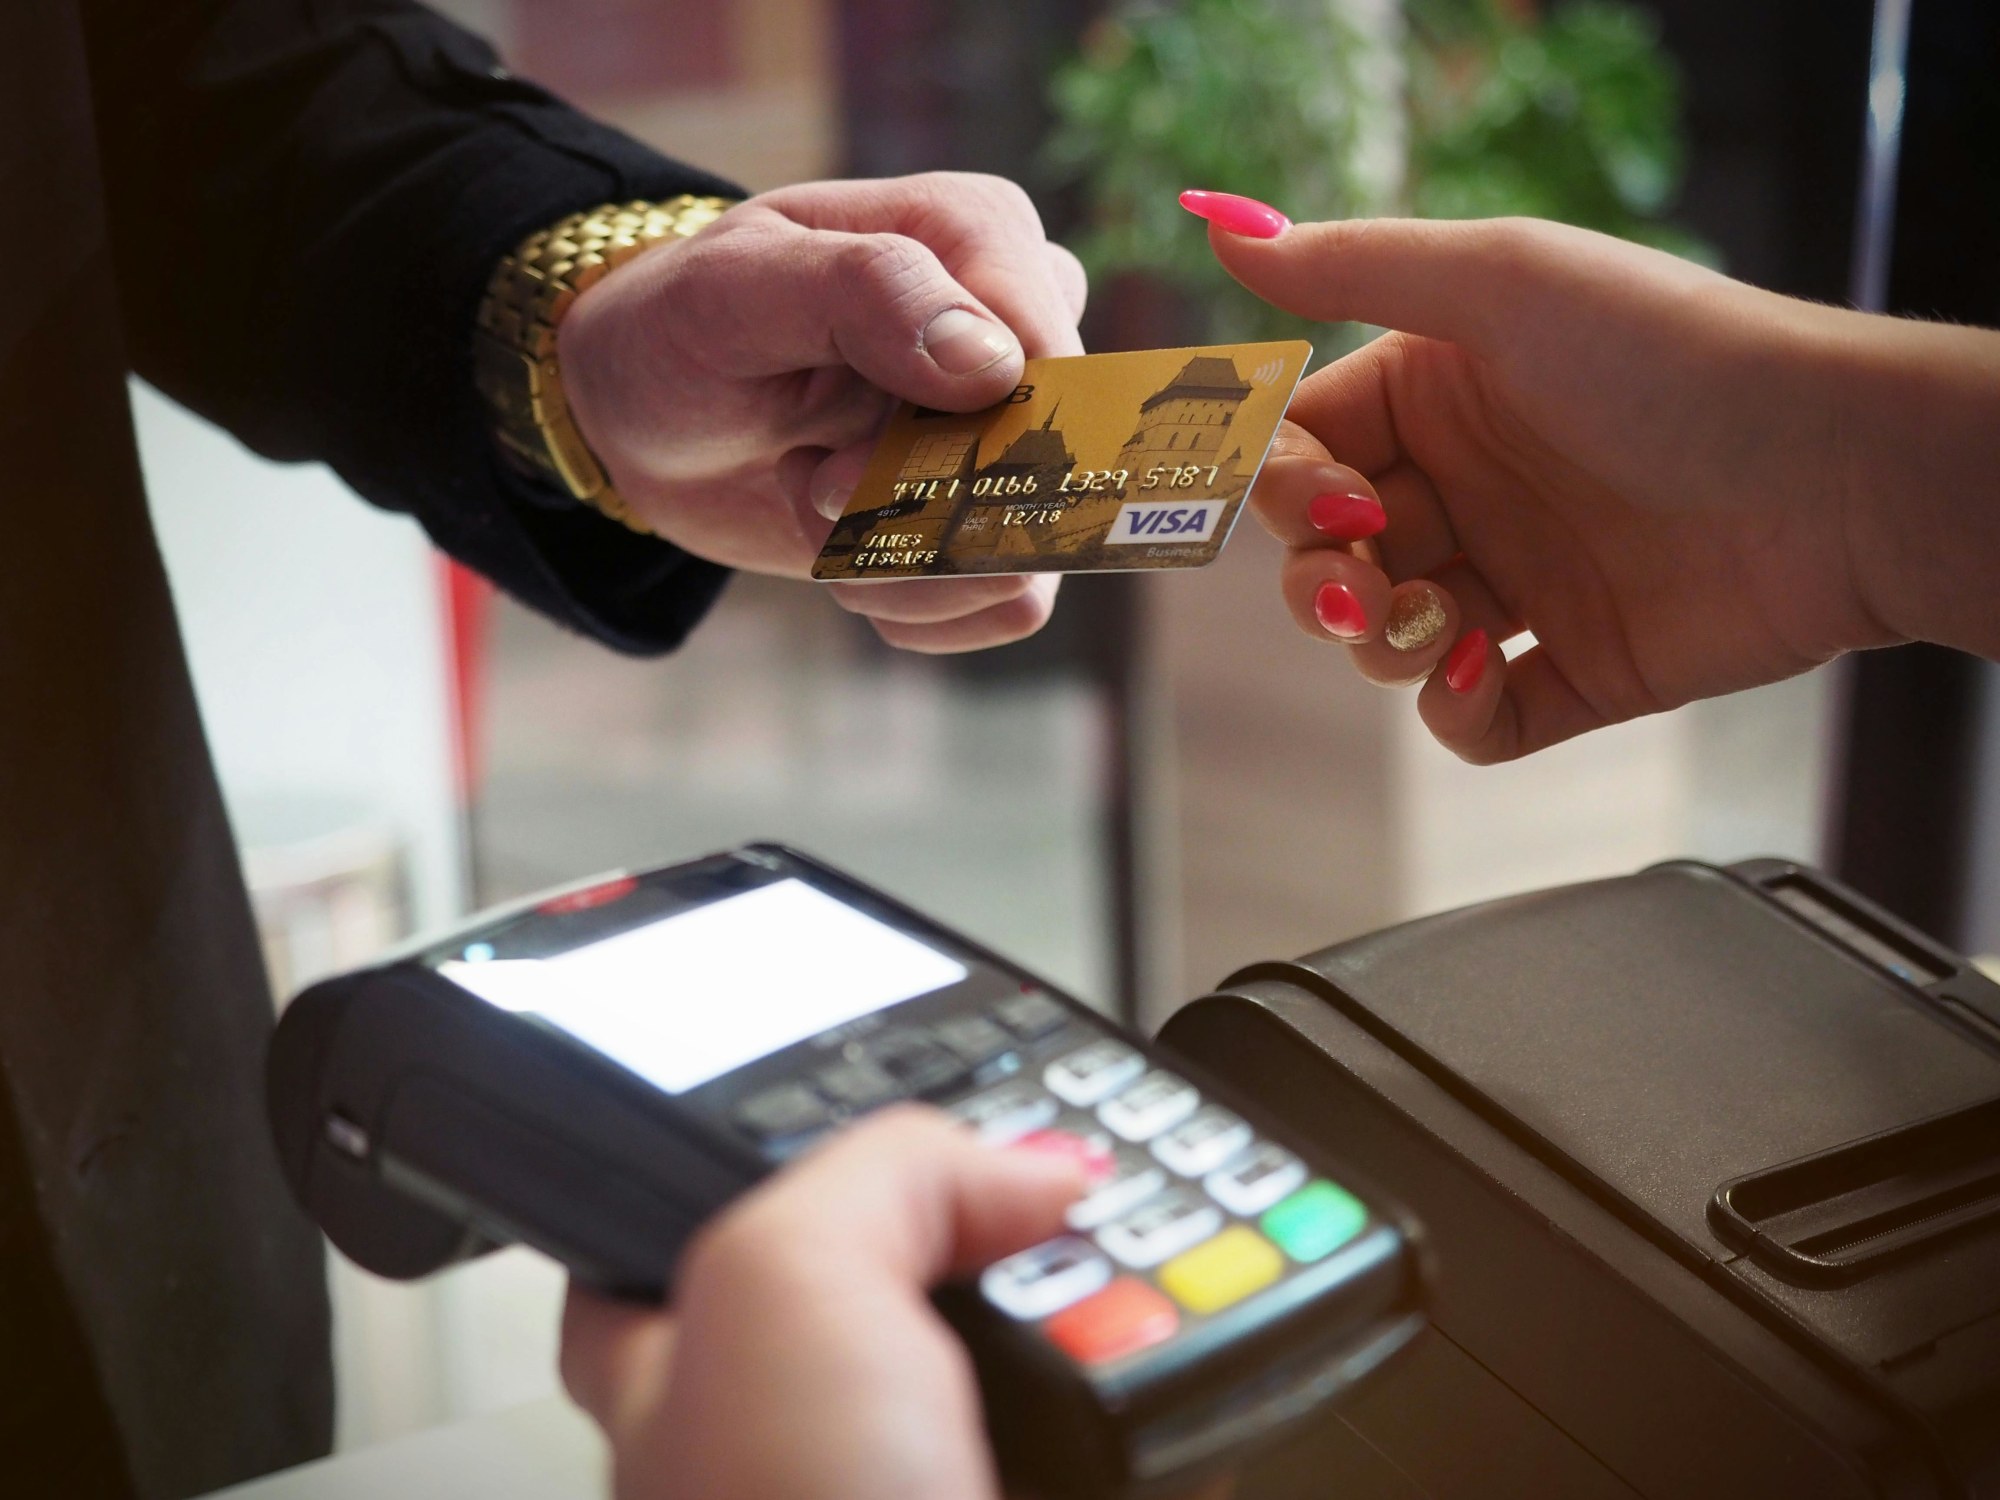
Handing over your hard-earned money to the bank may make you anxious, but it’s a better way to protect and grow your savings.
Here are some reasons why keeping your money in a bank is the better choice for your savings:
Liquidity
Banks have many financial products to offer, but if liquidity is really important, consider opening a high-interest savings account in a reliable bank. Keeping your cash at home may ensure that you can use it anytime, but its value may erode rapidly because your home vault or mattress offers no protection from inflation.
If you put your money in a bank, your cash will earn interest, even if the returns are smaller than other investments.

Control
You, as the depositor, has full control over your money and can make withdrawals anytime without having to worry about additional management fees or penalties.
Likewise, you may automate payment processes for your utilities and other bills if your money is in the bank.
Safety
Another advantage is that money deposited in authorised deposit-taking institutions are usually insured by the government for up to $250,000. This means depositors can get their deposit of up to $250,000 back if the bank suddenly closes down or its vaults are engulfed by flames.
Likewise, your money is somewhat protected from the effects of inflation because it earns an interest as long as your account is eligible.
Growth
Your money can grow in the bank from the interest your account earns each year. While interest rates may often be low for savings accounts, this still beats zero growth when compared with keeping the money in your home.
Furthermore, you will have a variety of banks and account types to choose from, so there’s always the possibility of earning more from a higher interest rate. One such bank product is a certificate of deposit (CD), more commonly called “term deposit” (TD).
A CD or TD is a type of time deposit savings account that offers account holders a higher interest rate. This can guarantee fixed returns that account holders would receive upon maturity – or at the end of their chosen lock-in term.
Most TDs don’t allow early withdrawals, but some banks may permit it if the account holder agrees to pay the early withdrawal penalty.
Explore nestegg for more information about banks, saving and investing.