

The original European Chips Act, which came into force in September 2023, has already catalysed over €80 billion in investments in chip manufacturing capacity. Despite these efforts, Europe still accounts for just 10% of the global semiconductor market. The new proposal aims to double this share to 20% by 2030, a target set against a backdrop of rapid expansion in the US and Asian semiconductor sectors.
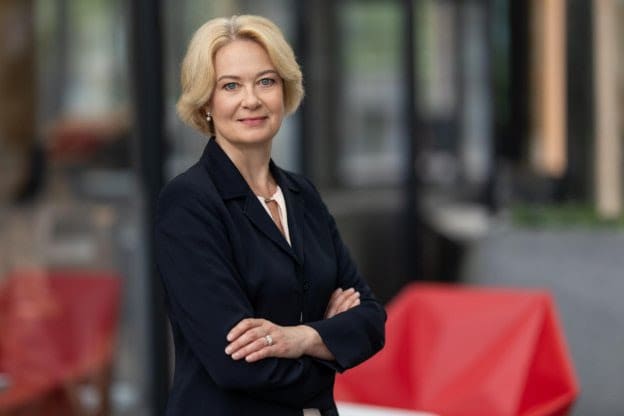
Daiva Rakauskaitė, a partner and fund manager at Aneli Capital, has been vocal about the need for systemic changes to ensure the success of the Chips Act II. "Europe can significantly improve its attractiveness for chip companies by making investment conditions faster and more predictable," she says. Rakauskaitė highlights that semiconductor projects operate on short innovation cycles and require substantial upfront capital, making delays in permitting and fragmented state-aid processes detrimental to competitiveness.
The demand for semiconductors continues to soar, with McKinsey estimating the global chip industry's value could reach $1.6 trillion by 2030. This has spurred European investors to increase their interest in the industry, with semiconductor start-ups raising a record €972 million in 2025. In the first quarter of 2026 alone, funding has already surpassed €380 million, according to PitchBook.
Despite this growing investor interest, Rakauskaitė argues that Europe’s main challenge remains the slow pathways to commercialisation. "Many young European deep tech companies face a difficult middle stage between research funding and commercial revenue," she explains. "Semiconductor start-ups in particular need expensive prototyping, testing, certification, and customer qualification before they can scale. Improving pathways to commercialisation would help more deep tech companies grow and strengthen the European ecosystem."
The recent Dealroom Deep Tech report underscores the potential of Europe’s deep tech landscape, noting that the continent is home to 30% of the world's top deep tech universities and produces twice as many science and engineering graduates as the US. Yet, the report also highlights a troubling trend: nearly 40% of deep tech unicorns with European founders have relocated to the US, either prior to or following funding rounds.
Rakauskaitė points out that one of the critical hurdles for deep tech start-ups is securing Series B+ funding. While Europe is on the verge of seeing several €1 billion-plus funds that could support these companies, she insists that systemic changes are necessary. "We need more flexible public-private financing, faster state-aid approvals, and stronger pension-fund participation in venture capital," she says.
The call for change is echoed by industry representatives and policymakers who acknowledge that current advancements are insufficient. They stress the importance of reducing bureaucratic barriers and creating a more conducive environment for innovation and growth in the deep tech sector.
As the European Commission prepares to release its Chips Act II proposal, the stakes are high for Europe's semiconductor and deep tech industries. The success of this initiative will hinge on the continent's ability to streamline processes, enhance funding mechanisms, and capitalise on its rich scientific and engineering talent pool.
The coming weeks will be crucial as stakeholders from across the industry eagerly await the details of the new proposal. The hope is that the Chips Act II will not only address the immediate challenges but also lay the groundwork for a robust and competitive European semiconductor ecosystem.